What difference could a lower home loan rate make?
What difference could a lower home loan rate make?
Eight times a year the Reserve Bank of Australia (RBA) Monetary Policy Boards meets to decide whether to increase, decrease, or maintain the cash rate. The decision that it makes each time flows through to home loan interest rates.
It’s important to know, though, that the RBA cash rate isn’t the only thing that affects home loan interest rates. The interest rate you’re being charged by your lender could also be based on your personal credit worthiness, your value as a customer and what the competition are offering.
There can be an interest rate difference of more than 2% in variable home loan rates on the market. So, it’s worth checking the market from time to time.
What to think about before you switch home loans
Refinancing your home loan to take advantage of a lower interest rate might save you money. Before you switch, make sure the benefits outweigh the costs.
Comparison websites can be a useful way to compare products, but they are businesses and may make money through promoted links. They may not cover all your options
Ask your current lender for a better deal first
Tell your current lender you are planning to switch to a cheaper loan offered by a different lender. To keep your business, your lender may reduce the interest rate on your current loan.
If you have at least 20% equity in your home, you’ll have more to bargain with. Having a good credit score will also help with negotiations. Compare any loan they offer you with the other loans you’re considering.
Check whether you’ll have to pay lender’s mortgage insurance
If you have less than 20% equity in your home, you might have to pay lender’s mortgage insurance (LMI). This can increase the cost of switching and outweigh the savings you’ll get from a lower interest rate.
If you decide to switch, ask for a refund of some of the LMI from your current loan
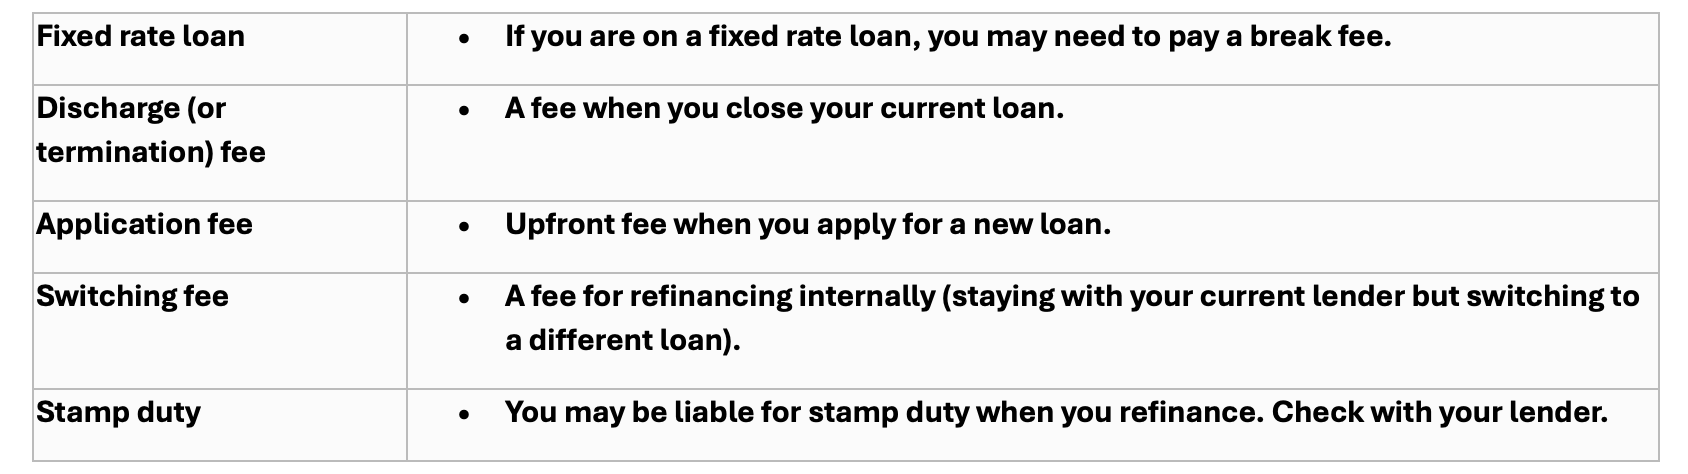
Compare these fees and charges:
Be clear on the length of the new loan
If you do switch, be firm on the length of home loan you want. Otherwise you could end up with a longer loan term than the years left to pay off your current mortgage.
The longer you have a loan, the more you’ll pay in interest. If you do decide to switch, negotiate a loan with a similar length to your current one